RiverTown St. Johns Riverfront Guide
St. Johns riverfront trails, kayak launches, and master amenities.
1. Micro-Market Real Estate Valuation & Neighborhood Trends
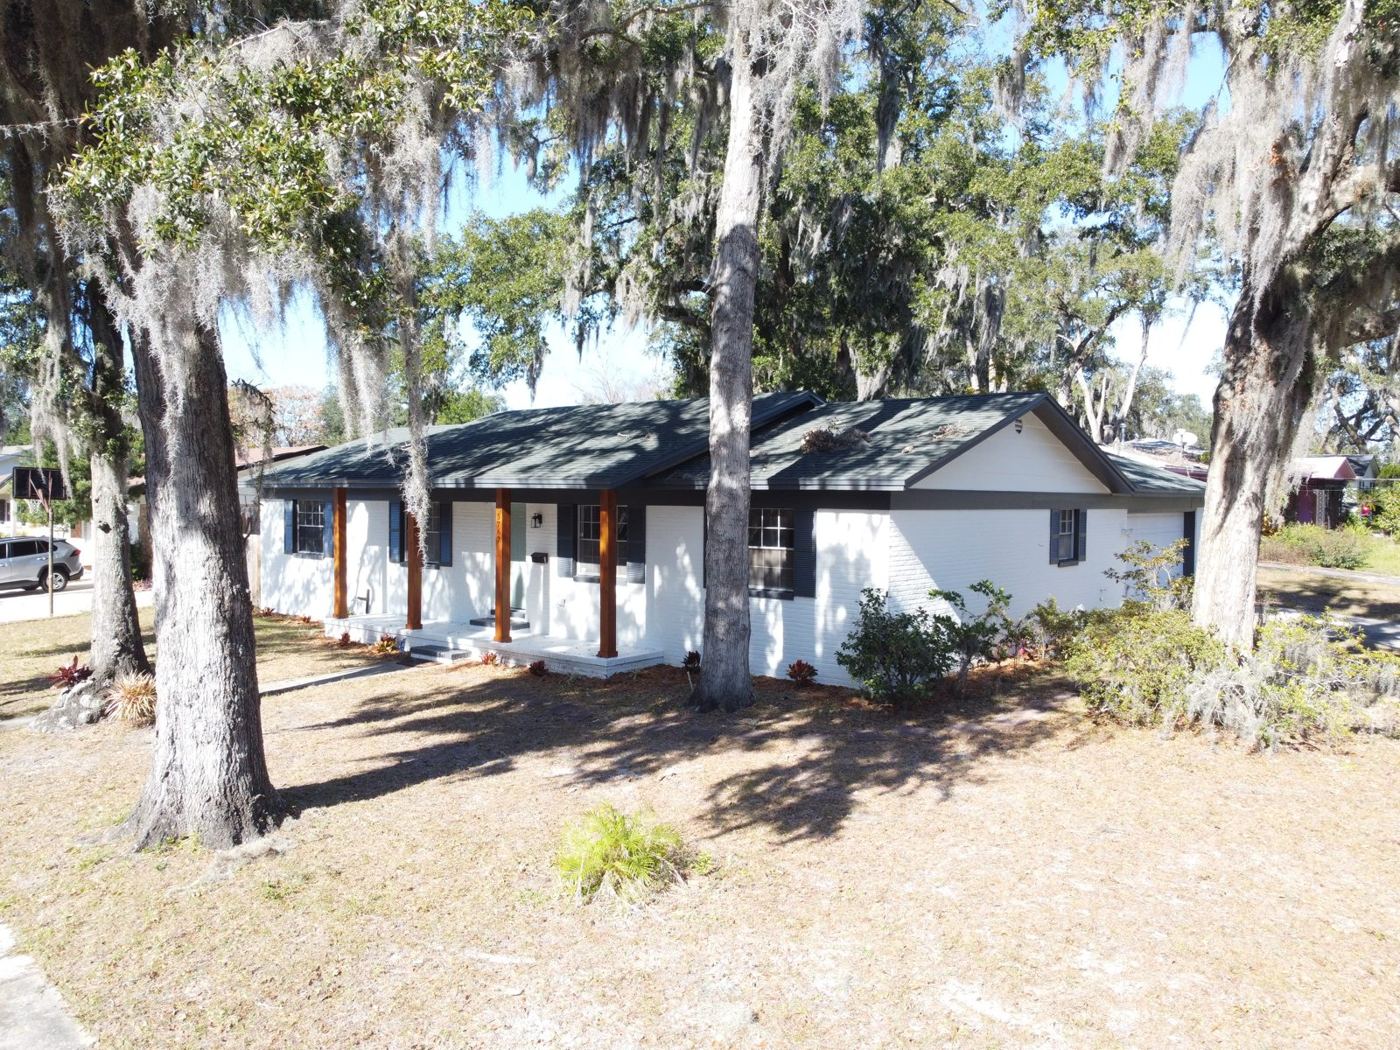
Analyzing real estate values in RiverTown St. Johns Riverfront Guide requires looking beyond headline metro medians. Pricing between neighboring subdivisions can differ meaningfully depending on school boundaries, CDD assessments and builder mix. Detached single-family homes in RiverTown St. Johns Riverfront Guide have maintained strong price stability due to robust buyer demand and controlled resale inventory. Recent pricing trends are best read from current comparables, not headlines. Johns Riverfront Guide have outperformed broader Florida averages. While condo-heavy markets faced inventory adjustments, single-family neighborhoods with top Florida DOE school rankings retained strong equity appreciation.
2. HOA Fees, CDD Bond Structures & School Zone Alignment
Homebuyers evaluating RiverTown St. Johns Riverfront Guide must account for total monthly carrying costs, including Community Development District (CDD) bonds and HOA dues. CDD assessments typically cover 30-year infrastructure debt and community amenity maintenance, while HOA fees manage common area landscaping and gate security. Understanding when CDD debt expires gives buyers significant long-term financial clarity.
School zone assignments remain a primary equity driver in RiverTown St. Johns Riverfront Guide. Zoned elementary, middle, and high schools in this area consistently achieve top academic ratings, attracting out-of-state relocations and sustaining home values.
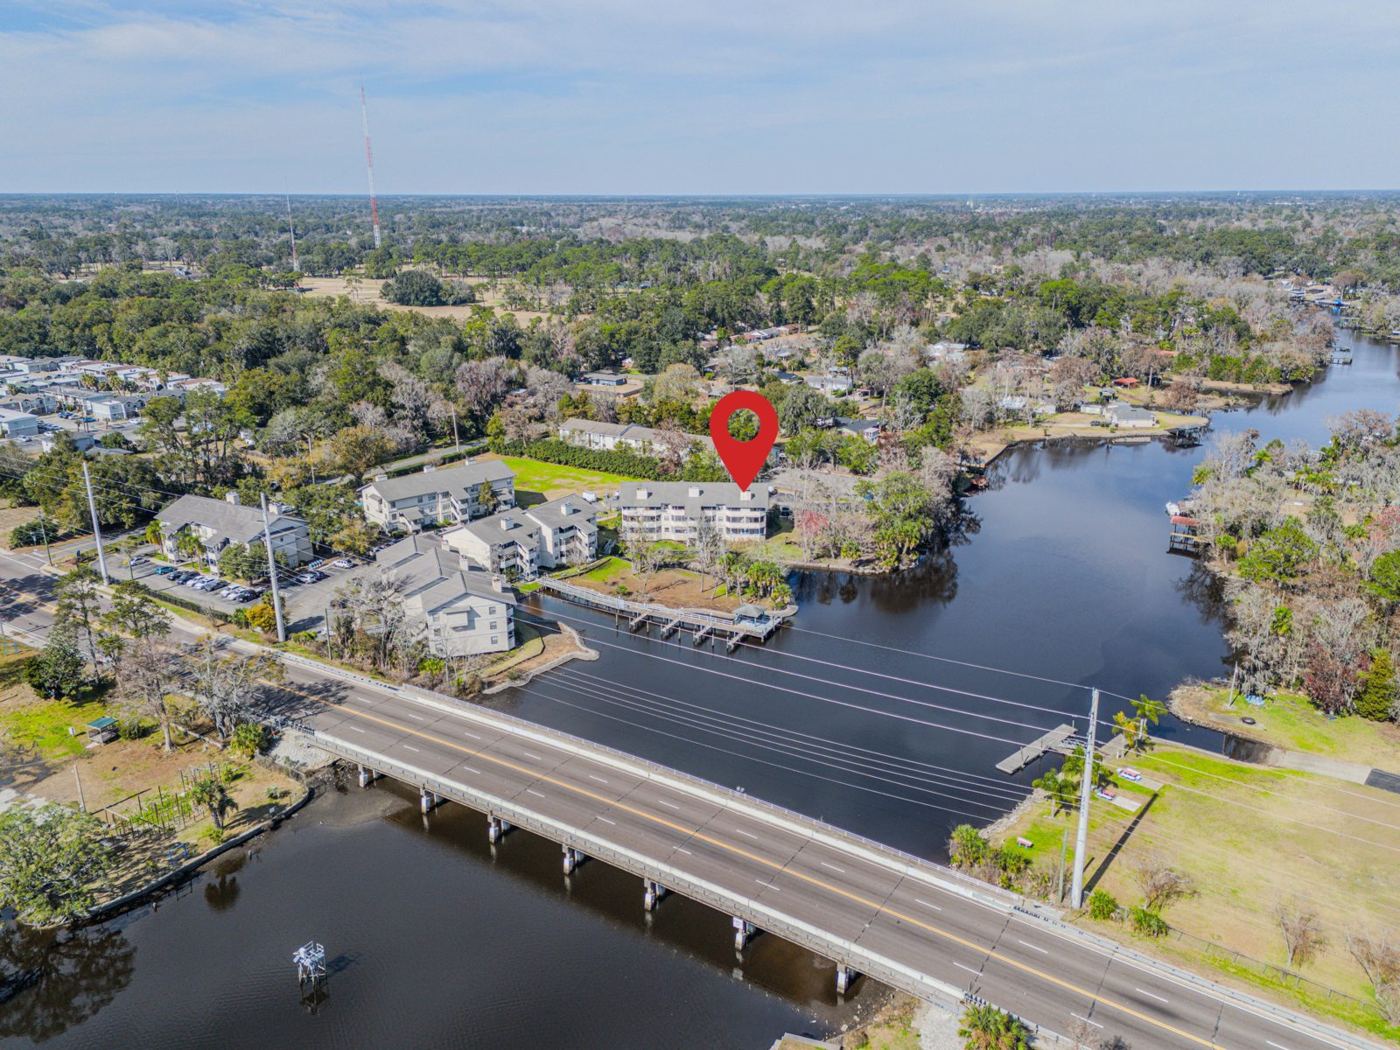
CDD balances, HOA dues, and school zoning all shift over time and by phase — verify the current figures for the specific address at the St. Johns County Property Appraiser and the St. Johns County school attendance zone lookup before you write an offer. Since this stretch of RiverTown runs along the St. Johns River, also confirm current flood elevation for the specific lot at FEMA's flood map service center.
Who RiverTown Fits
RiverTown suits someone who wants river access — kayak launches, a fitness trail along the water, a dock at the clubhouse — without leaving commuting distance to Jacksonville. That trade means a longer drive than staying inland in Putnam, but a shorter one than the coast, plus HOA and CDD costs that river towns inland don't carry. If a quiet stretch of the St. Johns matters more to you than square footage or acreage, this is the trade worth making; if you'd rather have more land for the same money, we can show you what that looks like closer to home.
3. Buyer & Seller Strategies with The Parham Team
When purchasing new construction or resale homes in RiverTown St. Johns Riverfront Guide, buyers should leverage 2-1 mortgage rate buydowns and seller closing concessions. Independent buyer representation ensures your inspection rights, lot selection, and incentives are protected from day one.
For sellers in RiverTown St. Johns Riverfront Guide, evaluating both instant cash offer options and open market MLS listings ensures you choose the strategy that maximizes net proceeds. Contact The Parham Team at (386) 530-1737 for a personalized home equity analysis.
Ready to Buy or Sell in RiverTown St. Johns Riverfront Guide?
Get an honest, data-driven market report from The Parham Team.Community Development District (CDD) assessments repay the bonds that built a community's infrastructure, typically over decades, and appear on the tax bill on top of any HOA dues. The amount differs by community and by phase — always pull the actual assessment for the specific lot. HOA fees cover common area maintenance. Evaluating whether CDD debt is expiring gives buyers significant leverage. Call The Parham Team at (386) 530-1737 and we'll pull the exact numbers for the address you're considering.
Q: What builder flex incentives are available for new construction?
A: Many builders offer incentive packages — often as rate buydowns or closing-cost credits through a preferred lender — and the amounts change month to month and community to community. Always get the current incentive sheet in writing and compare it against the total price, not in isolation. Bringing an independent buyer agent to your first visit protects your pricing rights. Homes zoned for highly rated schools often carry a price premium over otherwise comparable homes zoned elsewhere — the size of that premium shifts with the market, so compare recent sales on both sides of the boundary.
Q: What is the difference between an instant cash offer and listing on MLS?
A: A cash offer trades speed and certainty — an as-is close in days, no showings — against the open market, which usually nets more but takes longer and depends on condition, pricing and timing. Run both numbers side by side before deciding.